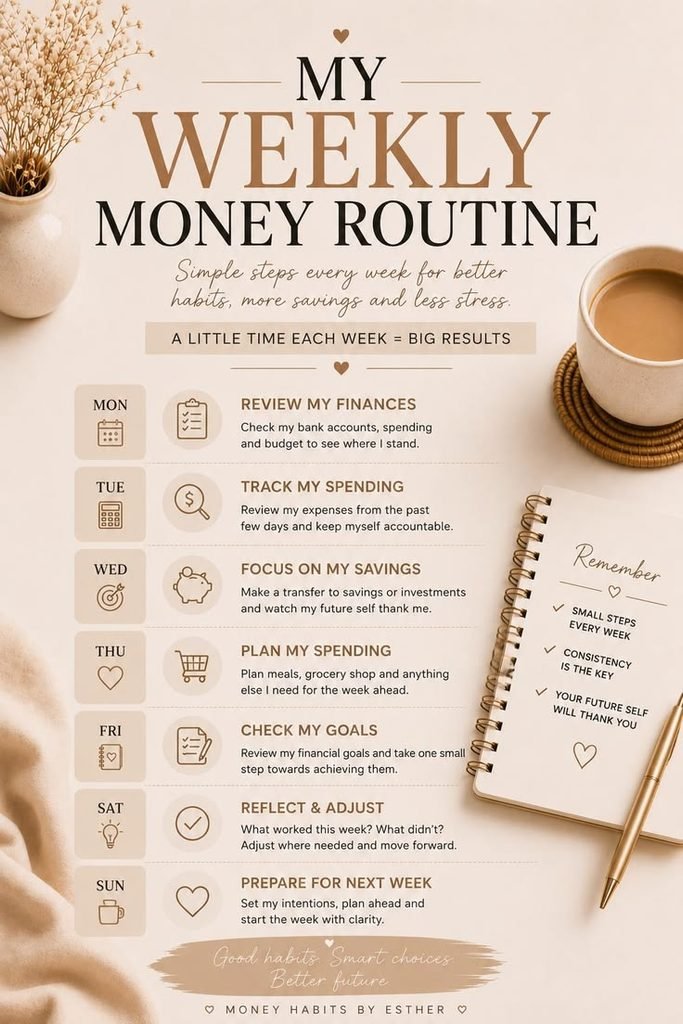
Managing money doesn’t have to mean spending hours studying spreadsheets or checking your bank account every few minutes.
A simple weekly money routine can help you stay aware of your income, expenses, savings, bills, and financial goals without making personal finance feel overwhelming.
Many financial problems develop because small things are ignored for too long. A subscription continues charging your account, a bill gets forgotten, or several small purchases quietly consume money that was supposed to go toward savings.
Spending a few minutes each week reviewing your finances can help you catch these problems earlier.
The good news is that a weekly money routine doesn’t need to be complicated. Once you create a system that works for you, the process can become a normal part of your week.
This guide explains what to check each week, how to organize your routine, and how to make money management easier to maintain.
What Is a Weekly Money Routine?
A weekly money routine is a short, regular period when you review and organize your finances.
Depending on your situation, your routine might take anywhere from 15 to 30 minutes.
During this time, you might:
- Check your bank accounts
- Review recent transactions
- Track your spending
- Check upcoming bills
- Review your budget
- Transfer money into savings
- Monitor financial goals
- Look for unusual charges
- Plan spending for the coming week
The purpose isn’t to control every single purchase.
It is simply to stay informed about what is happening with your money.
Why Have a Weekly Money Routine?
Checking your finances once a month can be helpful, but a weekly review gives you an opportunity to catch problems sooner.
For example, imagine you notice that your food spending is already higher than expected halfway through the month.
You still have time to adjust your spending.
Without checking until the end of the month, you might discover the problem after your budget has already been exceeded.
A weekly routine can help you:
- Stay aware of your spending
- Avoid forgotten bills
- Detect unexpected transactions
- Keep savings on track
- Plan upcoming expenses
- Reduce financial surprises
- Review progress toward goals
- Make better spending decisions
The routine is less about perfection and more about awareness.
Choose a Consistent Day
The easiest way to create a weekly money routine is to choose one specific day.
For example:
Sunday evening
or
Friday afternoon
or another day that fits your schedule.
Try to choose a time when you’re usually available and unlikely to be distracted.
You don’t need to spend your entire evening doing it.
Even 15 minutes can be enough for a basic review.
The important thing is consistency.
Step 1: Check Your Bank Accounts
Start your weekly review by checking your current balances.
If you have multiple accounts, review each one.
For example:
- Everyday spending account
- Savings account
- Emergency fund
- Other accounts used for specific financial goals
You don’t need to move money around immediately.
First, understand what you currently have available.
This can help you avoid spending money that is already needed for an upcoming bill.
Step 2: Review Recent Transactions
Look through your recent transactions.
Check for:
- Grocery purchases
- Transportation costs
- Restaurant spending
- Online purchases
- Subscriptions
- Utility payments
- Debt payments
- Transfers
- Other recurring charges
You may notice purchases you forgot about.
You may also identify transactions that don’t look familiar.
If you see a charge you don’t recognize, investigate it promptly through your bank or card provider.
Regularly reviewing transactions can help you stay aware of what’s happening in your accounts.
Step 3: Update Your Spending Tracker
If you use a spreadsheet, notebook, or budgeting application, update it once a week.
For example:
| Category | Weekly Spending |
|---|---|
| Groceries | $65 |
| Transportation | $30 |
| Restaurants | $25 |
| Entertainment | $15 |
| Shopping | $20 |
| Other | $10 |
| Total | $165 |
The exact categories and amounts will differ from person to person.
The important thing is to record enough information to understand your spending patterns.
Step 4: Compare Spending With Your Budget
Now compare your actual spending with the limits you established.
Suppose you created these monthly limits:
- Groceries: $300
- Restaurants: $100
- Entertainment: $75
- Shopping: $100
If you’re already halfway through the month but have spent most of your restaurant budget, that is useful information.
You can adjust your remaining spending rather than discovering the problem later.
A budget should guide your decisions, not make you feel guilty.
If your spending consistently doesn’t match your budget, the budget itself may need adjustment.
Step 5: Check Upcoming Bills
Look at the next one or two weeks and identify bills that are coming due.
These might include:
- Rent or mortgage
- Electricity
- Water
- Internet
- Phone
- Insurance
- Debt payments
- Subscriptions
- School-related expenses
- Other regular payments
Knowing what is coming can help you avoid spending money that you need for an upcoming obligation.
If a large bill is coming, you can plan around it instead of being surprised.
Step 6: Review Your Savings
Check whether you are still on track with your savings goals.
For example, suppose your goal is to save $1,200 during the year.
Your monthly target might be:
$1,200 ÷ 12 = $100 per month.
During your weekly review, you can check whether you’ve contributed the amount you planned.
If you are behind, don’t immediately assume you’ve failed.
Look at what happened and decide whether you can catch up gradually or need to adjust the timeline.
Step 7: Make Your Planned Savings Transfer
If your budget allows, make your regular savings contribution.
For example:
Weekly savings target: $25
After four weeks:
$25 × 4 = $100.
You can keep your savings in an account that is appropriate for your goals and circumstances.
If your bank supports automatic transfers, you may also be able to automate this process.
Make sure the amount you transfer doesn’t interfere with essential expenses or upcoming payments.
Step 8: Look for Unnecessary Expenses
Your weekly review is a good opportunity to identify spending that you didn’t really need.
Look for things such as:
- Unused subscriptions
- Repeated convenience purchases
- Unplanned online shopping
- Frequent takeout
- Unnecessary fees
- Purchases made without planning
Don’t automatically assume every optional expense is bad.
The goal is to determine whether your spending reflects your priorities.
For example, if you regularly pay for a subscription you never use, canceling it could free up money for something more important.
Step 9: Check Your Financial Goals
Take a moment to review your current financial goals.
These might include:
- Building an emergency fund
- Paying down debt
- Saving for education
- Saving for a major purchase
- Building long-term savings
- Reducing monthly expenses
Ask yourself:
Am I still moving toward this goal?
You don’t need to make progress every single week.
Sometimes the most important thing is simply making sure your plan hasn’t been forgotten.
Step 10: Plan Your Spending for the Coming Week
Once you’ve reviewed the previous week, plan for the next one.
Think about upcoming expenses.
For example:
- Do you need groceries?
- Are you attending an event?
- Do you need transportation?
- Is a bill due?
- Do you expect any unusual expenses?
Planning ahead can reduce impulse spending.
If you know you’ll need groceries, make a list before shopping.
If you know you have an event coming up, include the expected cost in your plan.
Step 11: Review Your Subscriptions
Subscriptions are worth checking periodically because recurring payments can be easy to forget.
You don’t necessarily need to review every subscription every week, but make it part of a broader monthly review.
Ask:
- Do I still use this service?
- Is it worth the cost?
- Has the price increased?
- Do I have duplicate services?
- Can I switch to a cheaper plan?
Even a small recurring charge can become significant over a year.
For example:
$10 per month × 12 months = $120 per year.
Understanding the annual cost can make recurring expenses easier to evaluate.
Step 12: Look for Bank and Service Fees
Check your transactions for fees.
These could include:
- Account fees
- ATM fees
- Late-payment fees
- Foreign transaction fees
- Service charges
Not every fee can be avoided, but identifying recurring fees can help you determine whether a cheaper option is available.
If you don’t understand a fee, contact the relevant financial institution or service provider and ask for an explanation.
Step 13: Review Debt Payments
If you have debt, include it in your weekly financial review.
Check:
- Upcoming payment dates
- Minimum payment requirements
- Current balances
- Additional payments you planned
- Interest or other applicable charges
Make sure required payments are included in your budget.
If you’re working toward paying debt faster, track your progress over time.
Avoid taking on additional debt simply because you’ve made progress elsewhere unless it fits into a plan you can reasonably manage.
Step 14: Keep an Eye on Irregular Expenses
Not every expense arrives every week or month.
Some expenses may occur only a few times a year.
Examples include:
- Vehicle repairs
- Insurance renewals
- School costs
- Holidays
- Birthdays
- Home maintenance
- Annual subscriptions
During your weekly routine, keep upcoming irregular expenses in mind.
If you know a $600 expense is coming in six months, for example, you could consider setting aside approximately:
$600 ÷ 6 = $100 per month.
Planning ahead can make large expenses easier to manage.
Step 15: Keep Your Routine Short
One reason people stop budgeting is that they make the process too complicated.
You don’t need to spend hours analyzing every transaction.
A basic weekly routine could take only 15 minutes:
Minutes 1–3
Check account balances.
Minutes 4–7
Review recent transactions.
Minutes 8–10
Check upcoming bills.
Minutes 11–13
Review savings and financial goals.
Minutes 14–15
Plan spending for the next week.
If you need more time, take it.
But don’t feel that a financial review has to become a major project.
A Simple Weekly Money Checklist
Use this checklist each week:
- Check bank balances
- Review recent transactions
- Update spending tracker
- Compare spending with your budget
- Check upcoming bills
- Review savings progress
- Make planned savings contributions
- Check financial goals
- Review unusual or unnecessary expenses
- Plan spending for the coming week
You can save this checklist in your phone or keep it next to your budgeting spreadsheet.
Example of a Weekly Money Routine
Imagine someone receives income twice a month.
Every Sunday evening, they spend about 20 minutes reviewing their finances.
Sunday Review
Bank balance: $850
Upcoming bills: $300
Available flexible spending: $550
Savings target: $50
Weekly grocery budget: $75
Entertainment budget: $25
They review their transactions and notice they spent $120 on restaurant meals during the previous week.
Instead of ignoring the situation, they adjust their plans for the next week.
They decide to prepare more meals at home and reduce restaurant spending.
The following week, they check again.
This simple process helps them make decisions based on actual information rather than guessing.
What If You Overspend?
Overspending occasionally doesn’t mean your entire financial plan has failed.
The important thing is to understand why it happened.
Ask yourself:
- Was there an unexpected expense?
- Did I forget to budget for something?
- Did I make several impulse purchases?
- Was my spending limit unrealistic?
- Can I adjust another category?
- Should I change my budget next month?
The answer can help you improve your system.
If the same category is consistently over budget, consider whether the spending limit is realistic.
What If Your Income Changes?
A weekly money routine can be particularly useful when your income isn’t consistent.
If your income comes from freelancing, commissions, self-employment, or other variable sources, check your expected income regularly.
During your weekly review, consider:
- Money already received
- Money expected soon
- Upcoming essential expenses
- Current savings
- Outstanding payments
During lower-income periods, prioritize essential expenses and avoid assuming that future income will definitely arrive.
During stronger months, you may have more flexibility to build savings or address other financial priorities.
Tools You Can Use
You don’t need an expensive financial-management system.
You can create a weekly routine using:
Spreadsheet
Useful if you want detailed tracking and calculations.
Budgeting App
Convenient for people who prefer mobile tracking.
Notebook
A simple option for people who prefer writing things down.
Bank Statements
Useful for reviewing transactions and recurring charges.
Calendar
Helpful for tracking bill due dates and financial deadlines.
Choose the method that you are most likely to maintain.
Common Mistakes to Avoid
Checking Only When Something Goes Wrong
Don’t wait until your account is nearly empty before looking at your finances.
Tracking Only Large Purchases
Small purchases can also add up.
Forgetting Upcoming Bills
Always look ahead so that upcoming payments don’t surprise you.
Making the Routine Too Complicated
A simple system you actually use is better than a perfect system you abandon.
Ignoring Financial Goals
Your weekly review should connect everyday spending with your larger financial priorities.
Feeling Guilty About Every Purchase
The purpose of budgeting is awareness and planning, not constant guilt.
How Long Should a Weekly Money Routine Take?
For many people, 15 to 30 minutes is enough for a basic weekly review.
However, your routine may take longer if you have:
- Multiple income sources
- Several bank accounts
- A business
- Significant debt
- Many recurring expenses
- Complex financial goals
The exact amount of time isn’t important.
Consistency is more valuable than spending a long time on your finances once and then ignoring them for weeks.
When Should You Do a Deeper Financial Review?
A weekly review is useful for everyday money management, but some tasks only need to be done monthly or periodically.
Once a month, consider reviewing:
- Total income
- Total spending
- Savings rate
- Debt balances
- Subscriptions
- Major financial goals
- Budget accuracy
Every few months, you might also review larger financial decisions and whether your current plan still fits your circumstances.
Final Thoughts
A weekly money routine doesn’t need to be complicated.
Spend a few minutes checking your accounts, reviewing transactions, looking at upcoming bills, tracking your spending, and checking your financial goals.
The purpose isn’t to control every purchase.
It’s to make sure you know where your money is going and that your everyday decisions are connected to your larger financial priorities.
You may not notice a dramatic difference after one week.
But repeating a simple financial routine week after week can help you become more organized, identify problems earlier, and make more intentional decisions with your money.
Start with 15 minutes this week.
Once the routine becomes familiar, you can adjust it to fit your own financial situation.
Leave a Reply