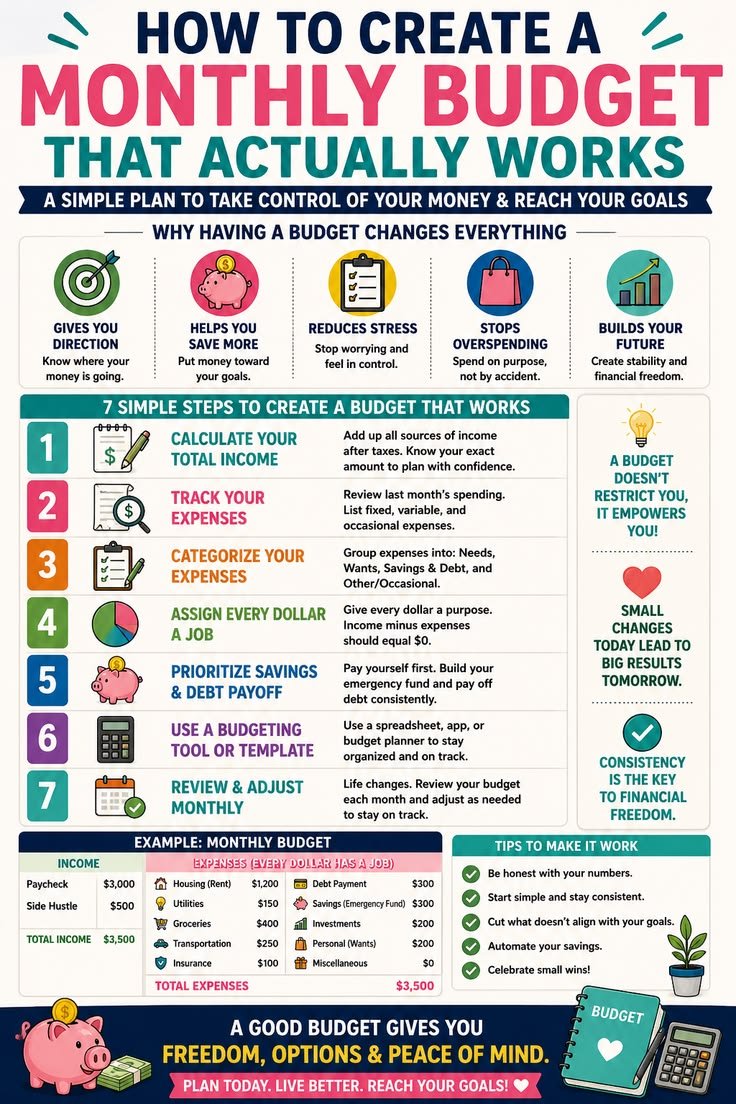
Managing money becomes much easier when you know exactly how much you earn, what you spend, and what you want your money to accomplish. A monthly budget gives you a simple way to organize your finances and make better decisions before your money disappears.
Many people think budgeting means cutting out everything they enjoy. In reality, a good budget is not about refusing to spend money. It is about deciding where your money should go so that your important expenses, savings, and personal goals are all considered.
Whether you have a regular salary, freelance income, part-time earnings, or income that changes from month to month, you can create a budget that fits your situation.
This guide explains how to build a realistic monthly budget from scratch and how to keep using it throughout the year.
What Is a Monthly Budget?
A monthly budget is a plan that shows how you intend to use the money you receive during a particular month.
A basic budget normally includes:
- Monthly income
- Housing costs
- Food and groceries
- Transportation
- Utilities
- Debt payments
- Insurance
- Savings
- Entertainment
- Personal spending
- Other financial goals
The purpose is to make sure your expected spending does not continually exceed your available income.
Instead of wondering where your money went at the end of the month, a budget allows you to make spending decisions before the money is gone.
Why Is a Monthly Budget Important?
Without a budget, it can be difficult to see how small purchases affect your finances over time.
You might pay for several subscriptions, order food regularly, make frequent online purchases, and spend money on transportation without realizing how much these expenses add up to.
A budget helps you identify these patterns.
It can also help you:
- Control unnecessary spending
- Prepare for upcoming bills
- Build savings
- Reduce debt
- Plan for large purchases
- Create an emergency fund
- Avoid relying on credit for everyday expenses
- Understand your financial habits
Most importantly, budgeting gives your money a purpose.
Step 1: Calculate Your Monthly Income
Start with the money you actually expect to receive during the month.
If you have a regular salary, this may be relatively simple. If you earn money from freelancing, commissions, self-employment, or multiple sources, you may need to estimate your income more carefully.
Include reliable sources of income such as:
- Employment income
- Freelance income
- Business income
- Part-time work
- Regular benefits or support
- Other predictable income
If your income changes every month, consider using a conservative estimate rather than assuming you will earn your highest possible amount.
For example, if your monthly income normally ranges between $1,800 and $2,200, you might build your essential budget around the lower figure.
This gives you some protection during a weaker month.
Step 2: List Your Essential Expenses
Next, write down the expenses you need to pay to maintain your basic living situation.
These may include:
- Rent or mortgage
- Basic groceries
- Electricity
- Water
- Transportation
- Insurance
- Phone service
- Necessary healthcare costs
- Minimum debt payments
Add these expenses together.
For example:
| Expense | Monthly Cost |
|---|---|
| Housing | $700 |
| Groceries | $300 |
| Utilities | $120 |
| Transportation | $100 |
| Phone | $50 |
| Insurance | $80 |
| Debt payment | $100 |
| Total | $1,450 |
If your monthly income is $2,000, you would have $550 remaining for savings, flexible expenses, and other goals.
Your actual numbers will depend on your location and circumstances.
Step 3: Separate Needs From Wants
One of the most useful budgeting exercises is separating necessary expenses from optional spending.
A need is something that is important for your basic financial and personal responsibilities.
A want is something that may improve your lifestyle but is not essential.
For example:
Needs
- Housing
- Basic food
- Utilities
- Transportation to work or school
- Required insurance
- Minimum debt payments
Wants
- Restaurant meals
- Entertainment
- New clothes when you already have enough
- Extra subscriptions
- Expensive hobbies
- Impulse purchases
This doesn’t mean you should eliminate all wants.
The purpose is simply to understand which expenses have the greatest flexibility when money becomes tight.
Step 4: Track Your Spending
Creating a budget is only the beginning.
You also need to compare your plan with what you actually spend.
For one month, record every purchase you make.
You can use:
- A notebook
- A spreadsheet
- A budgeting application
- Your bank statements
- A simple notes application
Record both large and small purchases.
A $3 or $5 purchase may seem insignificant, but repeated purchases can become a meaningful monthly expense.
At the end of the month, compare your actual spending with your budget.
You may discover that you spend more on food, transportation, shopping, or entertainment than you expected.
That information can help you create a more accurate budget next month.
Step 5: Choose a Savings Amount
Savings should be included in your budget instead of being treated as something you do only when money is left over.
Start with an amount you can realistically maintain.
For example, you might choose:
- $10 per week
- $25 per week
- $50 per month
- 5% of your income
- Another amount that fits your circumstances
The exact number matters less than building a consistent habit.
If your financial situation improves, you can increase your savings later.
Step 6: Consider Using the 50/30/20 Rule
One popular budgeting framework is the 50/30/20 rule.
Under this approach:
- About 50% goes toward needs
- About 30% goes toward wants
- About 20% goes toward savings and debt repayment
For someone earning $2,000 per month, that would look like:
- $1,000 for needs
- $600 for wants
- $400 for savings and debt repayment
However, this is a guideline rather than a universal rule.
Housing costs, income levels, family responsibilities, debt, and local living costs can make these percentages unrealistic for some people.
If your essential expenses already consume more than 50% of your income, don’t assume your budget has failed.
Use the framework as a starting point and adjust it to your circumstances.
Step 7: Budget for Irregular Expenses
Some expenses don’t happen every month.
That doesn’t mean you should ignore them.
Examples include:
- Annual insurance payments
- School expenses
- Vehicle repairs
- Home repairs
- Holidays
- Birthdays
- Property-related expenses
- Professional fees
- Annual subscriptions
Suppose you expect a $600 expense once a year.
Instead of being surprised when the bill arrives, you could set aside approximately $50 per month.
That way, the expense becomes easier to manage.
This approach is sometimes called a sinking fund.
Step 8: Create Categories for Your Spending
A simple budget becomes easier to manage when you divide your money into clear categories.
For example:
Housing
Rent, mortgage, maintenance, or other housing costs.
Food
Groceries, meals, and other food expenses.
Transportation
Fuel, public transportation, parking, vehicle maintenance, or similar costs.
Bills
Utilities, phone, internet, and other recurring services.
Debt
Required payments and additional debt repayment.
Savings
Emergency savings, short-term goals, and long-term savings.
Personal Spending
Entertainment, hobbies, shopping, and other optional expenses.
You can create more or fewer categories depending on how detailed you want your budget to be.
Step 9: Give Yourself a Spending Limit
A budget becomes easier to follow when you give flexible categories specific limits.
For example, instead of saying:
“I’ll try not to spend too much on restaurants.”
You could set a monthly restaurant budget of $100.
Once you approach that limit, you know you need to slow down your spending in that category.
The same approach can work for:
- Shopping
- Entertainment
- Takeout
- Hobbies
- Online purchases
A specific limit is often easier to follow than a vague intention.
Step 10: Automate Your Savings
If possible, make saving automatic.
You could schedule an automatic transfer shortly after receiving your income.
For example, if you decide to save $50 every payday and receive two paychecks per month:
$50 × 2 = $100 per month.
Over one year:
$100 × 12 = $1,200.
Automatic savings can reduce the temptation to spend the money before saving it.
Just make sure the transfer amount is appropriate for your available income and regular expenses.
Step 11: Review Your Subscriptions
Recurring payments are easy to overlook.
Review your bank or card statements and look for services you pay for every month.
Ask yourself:
- Do I still use this?
- Do I need it?
- Is there a cheaper option?
- Did I forget about this subscription?
- Would I sign up for it again today?
Canceling an unused service can immediately create room in your monthly budget.
You don’t necessarily need to cancel everything.
The goal is to make sure your recurring expenses match the value you receive from them.
Step 12: Create a Budget for Fun
A budget that allows no room for enjoyment can be difficult to maintain.
If your financial situation allows it, include some money for activities you enjoy.
This could include:
- Movies
- Restaurants
- Games
- Hobbies
- Social activities
- Personal purchases
The amount doesn’t need to be large.
The important thing is that your spending is intentional rather than accidental.
Step 13: Prepare for Emergencies
An emergency fund can protect your budget when an unexpected expense appears.
Examples might include:
- An urgent repair
- Unexpected travel
- A necessary replacement
- A temporary reduction in income
- Another genuine financial emergency
If you are starting from nothing, don’t worry about immediately building a large fund.
Start with a small target and increase it gradually.
For example:
Goal 1: $100
Goal 2: $500
Goal 3: $1,000
Goal 4: Continue building based on your circumstances.
The appropriate emergency savings target differs from person to person.
Step 14: Give Extra Money a Purpose
Sometimes you receive more money than expected.
This might come from:
- A bonus
- Overtime
- Freelance work
- Selling something you no longer need
- A refund
- A temporary side job
Instead of automatically spending all of it, decide beforehand how you want to use unexpected income.
For example:
$200 extra income
→ $100 to savings
→ $50 toward debt
→ $50 for personal spending
You can adjust these amounts according to your priorities.
Step 15: Review Your Budget Every Month
Your budget should not remain exactly the same forever.
Your income and expenses can change.
At the end of each month, ask yourself:
- Did I stay within my budget?
- Which category did I overspend in?
- Which expenses were lower than expected?
- Did I save what I planned?
- Did an unexpected expense appear?
- Can I reduce any recurring costs?
- Should I change next month’s spending limits?
Use the answers to create your next budget.
A budget becomes more useful as it becomes more accurate.
What If Your Expenses Are Higher Than Your Income?
This is one of the most important situations to identify.
If your monthly expenses are consistently higher than your income, you have a budget deficit.
For example:
Monthly income: $2,000
Monthly expenses: $2,200
Monthly shortfall: $200
In this situation, simply telling yourself to “save more” won’t solve the problem.
Instead, look for opportunities to either reduce major expenses or increase income.
Start with flexible expenses such as:
- Unused subscriptions
- Restaurant spending
- Entertainment
- Shopping
- Optional services
Then examine larger expenses where possible.
You can also consider ways to increase income, such as:
- Freelancing
- Part-time work
- Selling unused items
- Providing a service
- Overtime
- Additional work
The goal is to create a sustainable gap between your income and spending.
A Simple Monthly Budget Example
Imagine someone earns $2,500 per month.
Their budget might look like this:
| Category | Amount |
|---|---|
| Housing | $800 |
| Groceries | $350 |
| Utilities | $150 |
| Transportation | $150 |
| Insurance | $100 |
| Debt payments | $200 |
| Savings | $250 |
| Entertainment | $150 |
| Personal spending | $150 |
| Miscellaneous | $100 |
| Total | $2,400 |
This leaves $100 unallocated.
They could direct that money toward savings, debt repayment, an upcoming expense, or additional flexibility.
The example is only an illustration. A good budget should reflect your own income, expenses, priorities, and local cost of living.
Common Budgeting Mistakes to Avoid
1. Making the Budget Too Complicated
You don’t need twenty different categories if that makes the budget difficult to maintain.
Start simple.
2. Forgetting Irregular Expenses
Annual or occasional expenses can cause problems if they aren’t included in your financial planning.
3. Setting Unrealistic Limits
If you normally spend $300 on groceries, immediately budgeting $100 may not be realistic.
Make gradual changes when necessary.
4. Ignoring Small Purchases
Small purchases can add up when repeated frequently.
5. Treating the Budget as a Punishment
A budget should help you manage money, not make you feel guilty about every purchase.
6. Giving Up After One Bad Month
Unexpected expenses happen.
If you overspend one month, review what happened and start again.
One difficult month doesn’t mean your entire financial plan has failed.
How to Make Budgeting Easier
The best budget is one you can actually maintain.
Keep your system simple and review it regularly.
You can make the process easier by:
- Checking your account regularly
- Automating savings
- Setting spending limits
- Reviewing subscriptions
- Planning major expenses
- Tracking purchases
- Adjusting your budget when circumstances change
You don’t need a perfect system.
You need a system that helps you make better decisions consistently.
Frequently Asked Questions
How much of my income should I save each month?
There is no single percentage that works for everyone. Start with an amount you can maintain without falling behind on essential expenses, then increase it when your financial situation allows.
Is the 50/30/20 rule required?
No. The 50/30/20 rule is simply a budgeting guideline. Your personal budget may need different percentages depending on your income, housing costs, debt, family responsibilities, and other expenses.
Should I save money before paying debt?
It depends on your circumstances. Building a small emergency cushion can help prevent unexpected expenses from becoming new debt, while high-interest debt may also deserve significant attention. Consider both goals when creating your plan.
What should I do if I can’t save anything?
First, make sure your essential expenses are covered. If your income is not enough to cover basic costs, focus on stabilizing your finances, reducing major expenses where possible, and exploring legitimate ways to increase your income.
How often should I update my budget?
Reviewing your budget once a month is a practical starting point. You should also update it whenever there is a major change in your income or expenses.
Leave a Reply